How to Ease Into Homeownership with a 2:1 Buydown Funded by the Seller
In a high-interest-rate environment, buying a home can feel like stepping onto a financial treadmill set just a little too fast. For both first-time buyers trying to break into the housing market and experienced buyers looking to preserve cash, high monthly payments are often the biggest hurdle to homeownership.
Enter the 2:1 Buydown, a proven financing strategy that lowers your interest rate (and your monthly mortgage payment) for the first two years of your loan. Even better? The cost of this temporary rate reduction can be fully funded by the seller of the property through seller concessions.
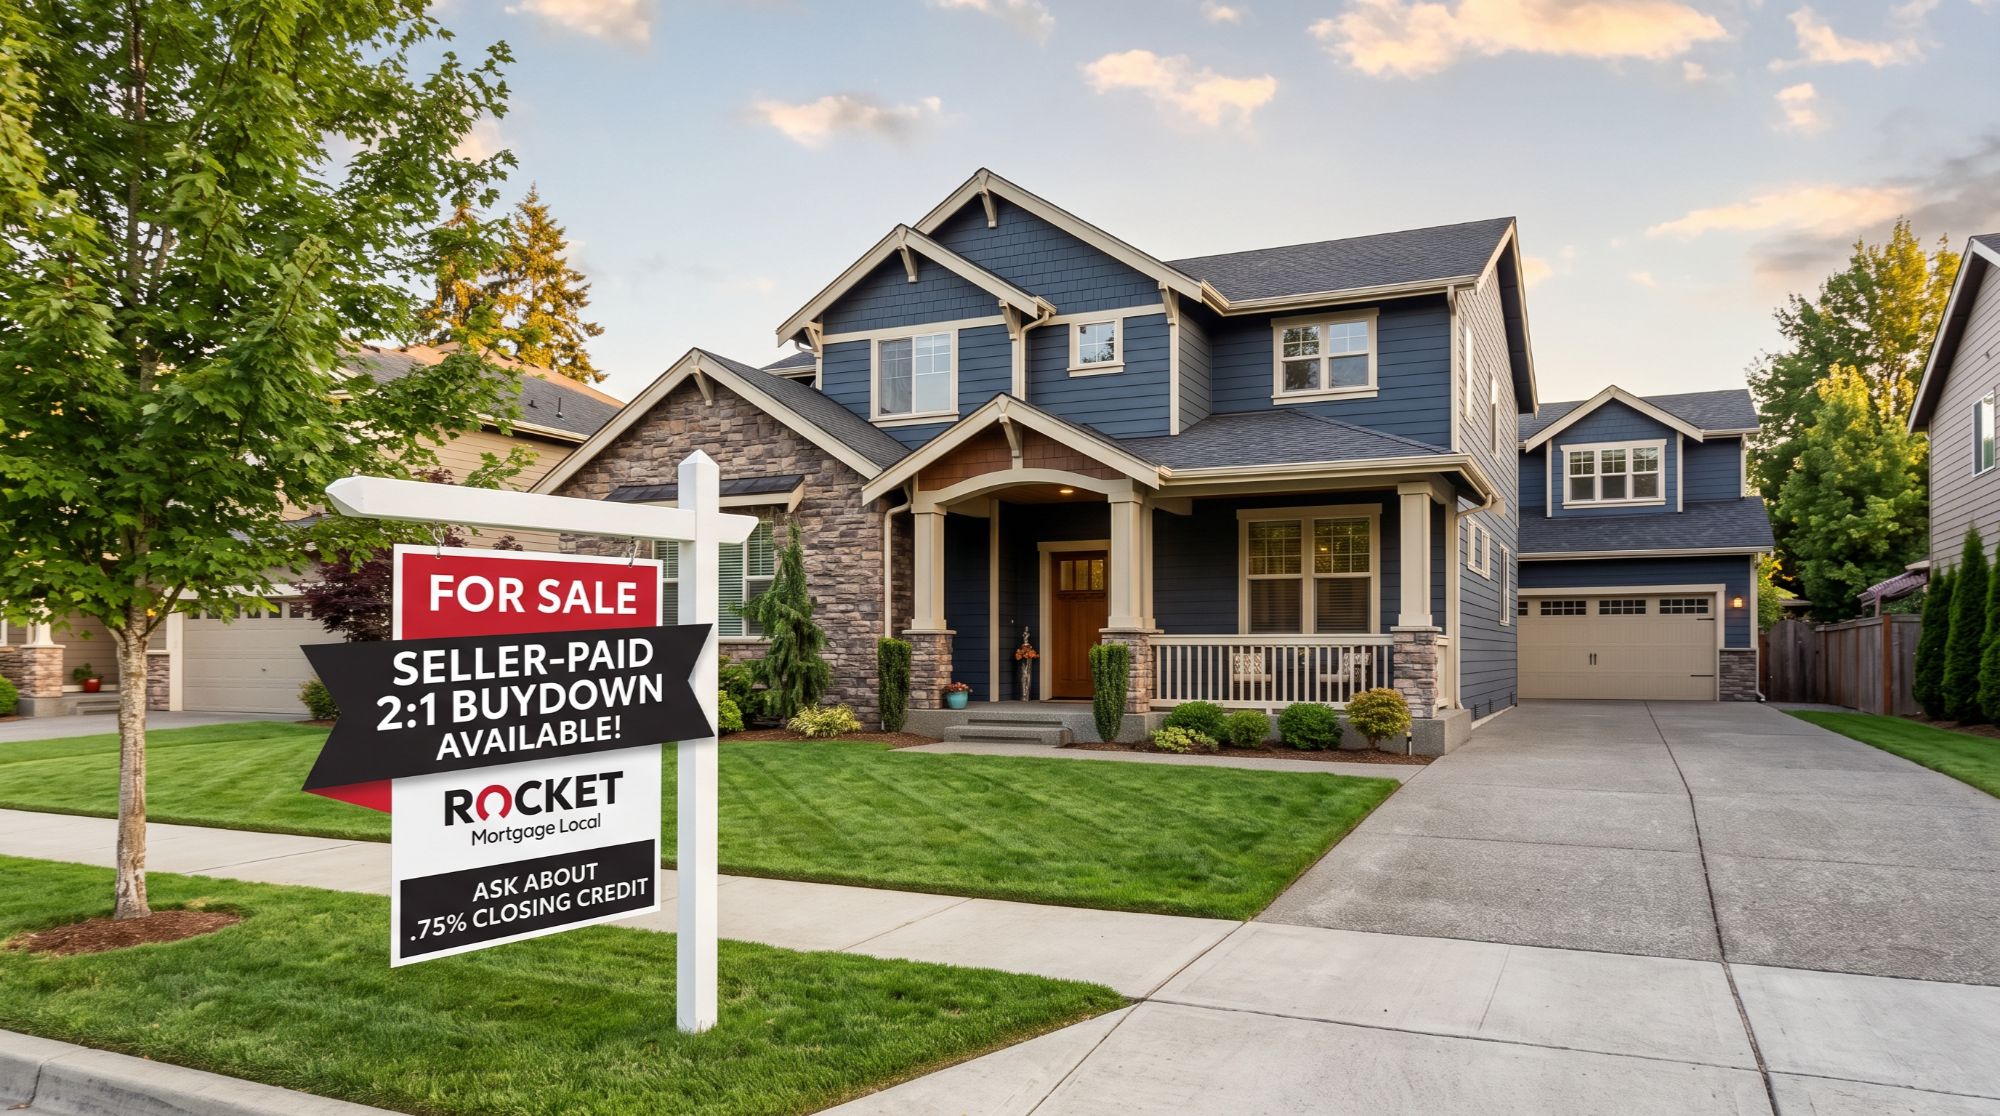
Working with Rocket Mortgage, buyers can pair a seller-funded 2:1 buydown with exclusive local perks to maximize their savings.
What Is a 2:1 Buydown?
A 2:1 buydown is a temporary rate reduction structure applied to a fixed-rate mortgage. It eases you into your full mortgage payment over a two-year step-up period:
-
Year 1: Your interest rate is 2% lower than your permanent note rate.
-
Year 2: Your interest rate is 1% lower than your permanent note rate.
-
Years 3 through 30: Your interest rate steps up to the full note rate for the remaining lifetime of the loan.
Unlike an Adjustable-Rate Mortgage (ARM), where rates can fluctuate unpredictably after a fixed period, a 2:1 buydown offers total predictability. Your full contract rate is locked in from day one—you are simply receiving a prepaid subsidy on your interest for the first 24 months.
How Does the Seller Fund the Buydown?
What the Seller Needs to Do:
-
Agree to Seller Concessions: During purchase contract negotiations, your real estate agent includes a provision requesting that the seller contribute a specific dollar amount toward seller concessions (also known as seller credits).
-
Provide the Closing Cost Credit at Closing: At closing, instead of reducing the sticker price of the home, the seller's agreed-upon credit is is added to the Buyer's side of the closing statement to pay for the Buydown.
Why Would a Seller Do This?
Sellers often prefer funding a rate buydown over cutting their list price. A price reduction of $10,000 to $15,000 might only save a buyer $60 to $80 a month, which rarely moves the needle. However, allocating that same $10,000 to $15,000 toward a 2:1 buydown saves the buyer hundreds of dollars every month during their first two years. It creates an enticing incentive for buyers while protecting the seller's property valuation benchmark in the neighborhood.
A Real-World Example: Buying a $500,000 Home at a 7.5% Note Rate
Imagine purchasing a residential property for $500,000 with a 10% down payment ($50,000), leaving a loan amount of $450,000 on a 30-year fixed mortgage at today's rate of 7.5%.
(Note: Calculations below reflect Principal & Interest payments. Property taxes, homeowner's insurance, and HOA fees remain separate.)
| Loan Period | Effective Interest Rate | Estimated Monthly P&I Payment | Monthly Savings vs. Note Rate |
| Year 1 | 5.5% (2% below note rate) | $2,555 | $591 / month |
| Year 2 | 6.5% (1% below note rate) | $2,844 | $302 / month |
| Years 3–30 | 7.5% (Full Note Rate) | $3,146 | Base Payment |
The Savings Breakdown:
-
First Year Total Savings: ~$7,092
-
Second Year Total Savings: ~$3,624
-
Total 2-Year Savings: ~$10,716
In this scenario, the seller contributes approximately $10,716 at closing to fund the buydown. That puts over $10,700 back into your pocket during your initial transition into the home, giving you crucial financial breathing room for moving costs, furniture, or emergency savings.
Extra Rocket Mortgage Benefit: The "Local" Loan Officer Advantage
When structuring a 2:1 buydown, working with the right lending partner makes all the difference.
When you work directly with a Rocket Mortgage "Local" Loan Officer, you unlock an exclusive lender benefit: a closing cost credit of 0.75% (75 basis points) of your total loan amount.
Using our $450,000 loan example:
This $3,375 credit from Rocket Mortgage helps pay down your third-party closing costs (such as title insurance, appraisal fees, or lender origination fees). Combining this lender credit with a seller-paid 2:1 buydown significantly reduces the cash required out of pocket at the closing table.
Key Rules to Keep in Mind
-
You Must Qualify at the Full Note Rate: Lenders qualify your income and debt-to-income (DTI) ratio based on the full contract interest rate (7.5% in our example), not the reduced Year 1 rate. This ensures you can comfortably afford the home long after the temporary buydown period ends.
-
Seller Concession Caps Apply: Conventional, FHA, and VA loans limit total seller concessions (e.g., up to 3%–6% depending on down payment and loan type). Your real estate agent and Rocket Mortgage Loan Officer will ensure the buydown cost fits within allowed guidelines.
-
Refinance Protection: If market interest rates drop in Year 1 or Year 2 and you decide to refinance early, any remaining, unused funds sitting in your buydown escrow account are automatically applied as a credit toward reducing your loan principal balance. You never lose that money.
Summary
A seller-funded 2:1 buydown is one of the smartest strategies available to buyers in today's high-rate market. It provides significantly lower payments when you need them most, keeps the purchase price intact for the seller, and paired with the 0.75% closing cost credit from a Rocket Mortgage Local Loan Officer, delivers maximum affordability with minimal upfront stress.
Call or email Bryan for assistance in making this work for you.
Categories
Recent Posts
Principal Premier Agent License ID: MD: 644396 | DC: SP40002306
+1(301) 525-7453 | bryan.kerrigan@redfin.com