Social Security’s 3.6% COLA Boost: What It Means for Retirees, Medicare & the Housing Market
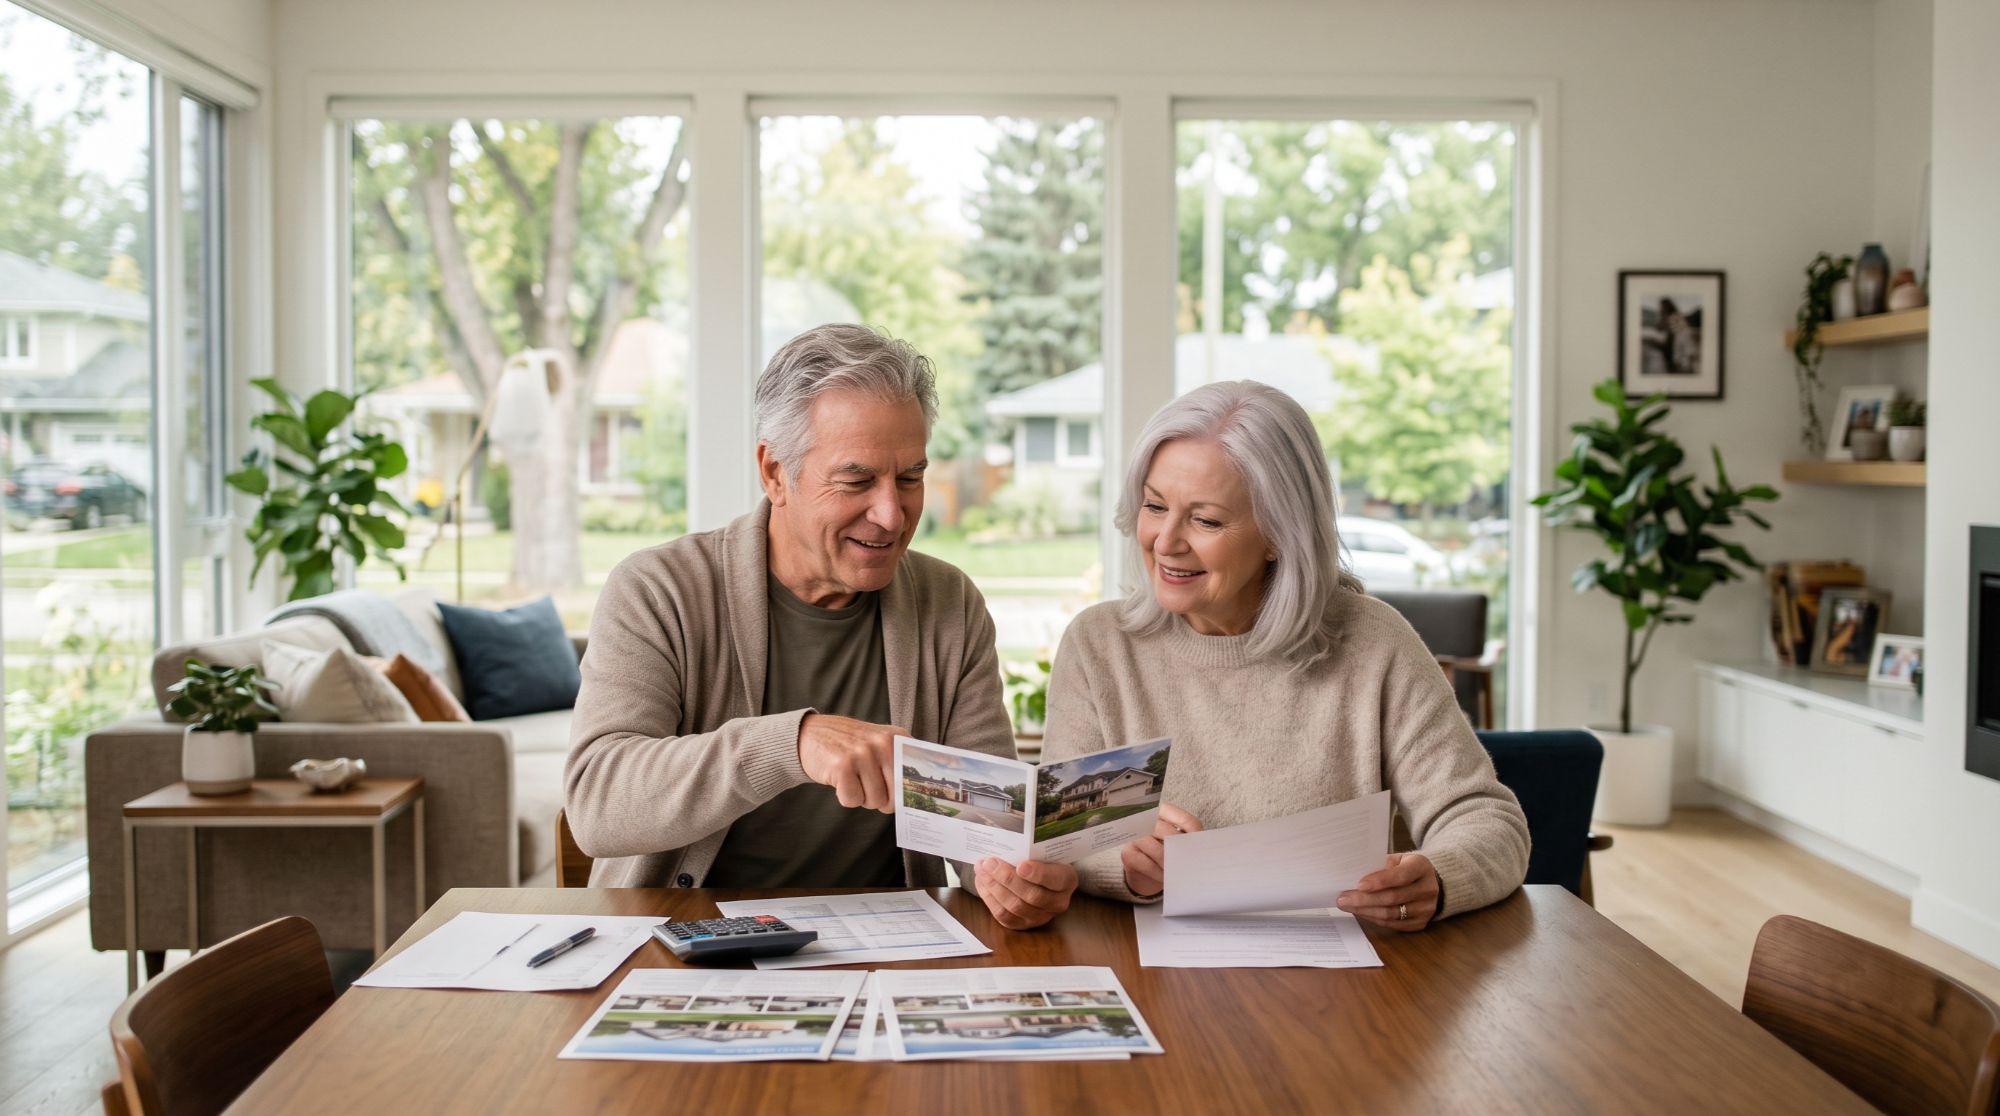
With the official approval of a 3.6% Cost-of-Living Adjustment (COLA) for Social Security benefits, millions of American retirees and beneficiaries are set to see a welcome bump in their monthly checks starting this January. For the average retired worker, a 3.6% increase adds roughly $70 to $75 per month in gross benefits.
While a monthly increase of $75 might seem like a modest sum on its own, its ripple effect extends beyond household groceries and utility bills, it directly influences buying power, debt-to-income ratios, and housing decisions for mature buyers and sellers.
The Real Estate Connection: How COLA Impacts Buyers and Sellers
Housing costs remain one of the largest budget line items for older adults. Whether planning to downsize, relocate closer to family, or purchase a low-maintenance home in a active-adult community, the 3.6% COLA adjustment influences real estate strategies in several key ways:
1. Improved Mortgage Qualification & Debt-To-Income Ratios
For retirees taking out a purchase mortgage or refinancing, lenders evaluate fixed monthly income to establish the Debt-to-Income (DTI) ratio. Because Social Security benefits represent steady, guaranteed income, a higher gross benefit increases a buyer's qualifying income floor. On a $500,000 home purchase or downsized condo purchase, every extra dollar of guaranteed income helps retirees satisfy lender underwriting criteria in high-interest environments.
2. Greater Flexibility for Downsizing and Selling
For older homeowners looking to sell a larger family home, a COLA increase provides extra buffer cash to absorb elevated moving expenses, temporary storage, or higher monthly HOA dues in managed condo or townhouse developments. Sellers can leverage the equity built up in their existing homes while relying on their newly increased fixed income to comfortably manage ongoing maintenance fees elsewhere.
3. Boosting Confidence in Active Retirement Communities
Retirees eyeing active-adult (55+) or golf course communities often balance fixed Social Security income against monthly community amenities fees. The steady upward adjustment in Social Security checks helps maintain purchasing confidence, preventing retirees from feeling priced out by neighborhood HOA adjustments.
The Catch: How Medicare Part B Increases Nibble at Net Savings
While a 3.6% COLA increase boosts gross benefit totals, retirees need to keep a close eye on the net check amount hitting their bank accounts.
For the vast majority of Social Security recipients, Medicare Part B premiums are deducted directly from their monthly benefit checks before the money is deposited. When Medicare Part B premiums rise, that deduction offsets part of the annual COLA gain.
-
Gross vs. Net Realities: If a retiree receives a $72 monthly COLA boost, but the standard Medicare Part B premium increases by $10 to $15 per month, the actual net gain drops closer to $55 or $60 per month.
-
Impact on Disposable Budgeting: While beneficiaries still retain a positive net increase overall, accounting for health insurance adjustments is essential when planning major financial moves, such as estimating a new home's monthly mortgage or HOA budget.
Summary for Buyers and Sellers
The 3.6% Social Security COLA adjustment is a positive financial step forward for older adults navigating today's housing market. While Medicare Part B deductions will absorb a portion of the gain, the net increase in steady, predictable monthly income gives retiree buyers more leverage at the mortgage table and greater peace of mind when transitioning into their next home.
Connect with Bryan Kerrigan if you are considering buying or selling a home in Maryland or Washington DC.
Categories
Recent Posts
Principal Premier Agent License ID: MD: 644396 | DC: SP40002306
+1(301) 525-7453 | bryan.kerrigan@redfin.com